
Tesco and Sainsbury's are well positioned to benefit from slower expansion by Aldi and Lidl, as competitive pressure across the UK grocery market becomes more manageable.
UBS analysts Sreedhar Mahamkali and Angelo Mangieri identified a more supportive trading environment for the two listed grocers in their latest UK food retail competition monitor. The bank's geospatial research shows industry store formation grew by just 1.3% year on year in the third quarter of 2026, below the pre-pandemic long-term average of 2.6%.
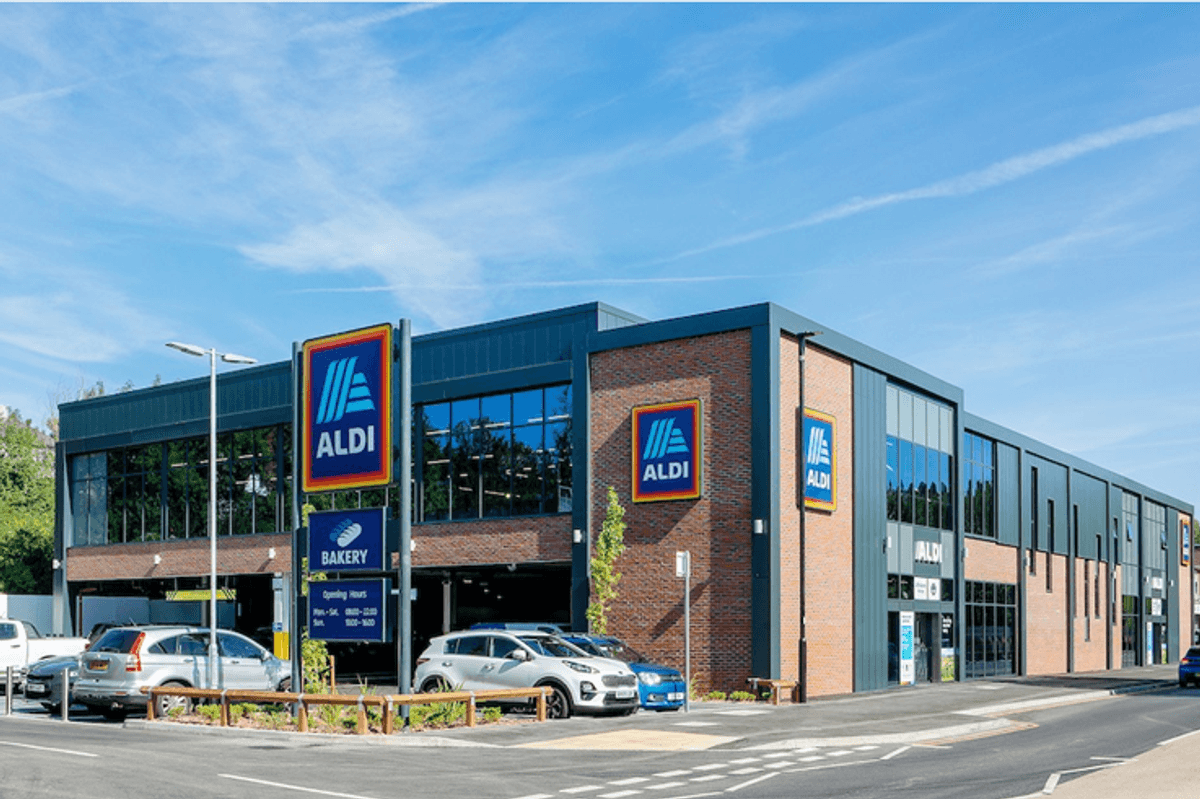
Aldi's UK store growth slowed to 3.3%, down from 4.3% in the first quarter, while Lidl's expansion reached 3.4%.
Both figures remain below their historical growth rates, with Aldi previously recording expansion of around 7% and Lidl also experiencing a marked slowdown since 2023.
Further expansion could become harder after the Competition and Markets Authority classified both chains as large grocery retailers, bringing more stringent planning and location restrictions.
Limited availability of space at retail parks, which have provided an important route for discounter expansion, adds another potential constraint.
UBS also highlighted growing cannibalisation, the extent to which new stores take business from existing outlets operated by the same retailer.
The proportion of Aldi stores facing competition from another Aldi outlet has reached 87%, compared with 72% in 2012, while Lidl's equivalent figure has risen to 85% from 73%.
Competitive overlap between the two discounters has also increased, reaching 94% for Aldi and 89% for Lidl.
The bank sees Tesco and Sainsbury's benefiting from this more mature competitive environment, alongside continued investment in price matching.
Tesco's Aldi Price Match range covered more than 900 products in September, up sharply from around 600 at the beginning of the year.
Sainsbury's maintained a comparable range of approximately 750 products, strengthening its ability to compete on customer perception and pricing.
UBS also highlighted Tesco's price leadership and retail media operations, while Sainsbury's focus on grocery following the Argos disposal offers potential for earnings and valuation improvement.